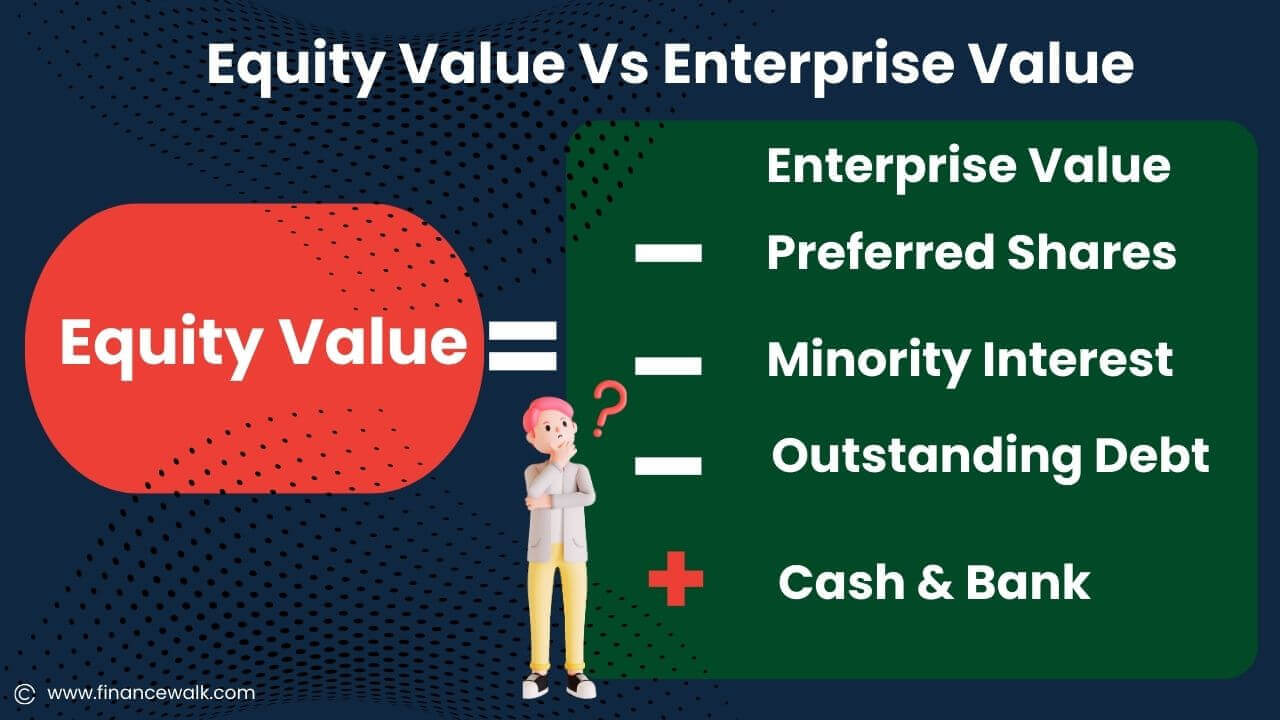
Equity value is the value attributable to a company’s equity holders. Enterprise value is a measure of the value of its operating business after adjusting for financing claims and non-operating assets. They answer different questions; neither is automatically more accurate.
The important distinction is between the value of the operating business and what belongs to the common shareholders. Keep that distinction consistent when you calculate a valuation, select a multiple or move from a business value to a value per share.
The basic formulas
For a listed company with one class of common shares:
Market equity value = share price × common shares outstanding.
A common enterprise-value bridge is:
Enterprise value = common equity value + debt + preferred equity + non-controlling interests − cash and cash equivalents.
That is a starting framework. The precise bridge depends on the valuation purpose, the scope of the operating business and how items such as leases, investments and other claims are treated. Do not add an item twice or deduct an asset already excluded from the business value.
A simple numerical bridge
Consider a fictional company. All amounts below are in millions except the share price.
| Item | Amount |
|---|---|
| Common shares outstanding | 10 million |
| Share price | 20 |
| Common equity value: 10 × 20 | 200 |
| Add debt | 60 |
| Add preferred equity | 10 |
| Add non-controlling interests | 5 |
| Subtract cash | (25) |
| Enterprise value | 250 |
In this example, enterprise value is 200 + 60 + 10 + 5 − 25 = 250. The common equity is worth 200 under the stated assumptions; 250 is not the amount belonging to the common shareholders.
Reverse the bridge
If your valuation produces an operating enterprise value of 250 on the same basis, common equity value is 250 − 60 − 10 − 5 + 25 = 200. Dividing by 10 million common shares gives 20 per share in this simplified case.
A real per-share calculation may also require treatment of options, restricted shares, convertible securities and other dilution. Use a consistent share count and claims adjustment rather than dividing by whichever share figure is easiest to find.
Market equity value is not book equity
Book equity is an accounting balance: recorded assets minus recorded liabilities, subject to the applicable accounting rules. Market equity value reflects the price of the ownership interest in the market. An estimated equity valuation reflects the assumptions and method used by the analyst.
For example, a company can have book equity of 80 and market equity value of 200. There is no requirement that they match. Using “assets minus liabilities” as the formula for market capitalization confuses accounting amounts with market value.
Why cash is subtracted and debt is added
The bridge separates the operating business from the financing and assets represented in the equity price. Adding debt brings another financing claim into the calculation. Subtracting cash removes an asset that is being treated separately from operations.
Be explicit about which cash is available and which is restricted or needed for the business. Do not describe all cash as freely distributable without examining it. Equally, adding all balance-sheet liabilities as debt is not a reliable shortcut.
Other adjustments need a consistent basis
- Preferred equity: account for its claim separately when it is outside common equity.
- Non-controlling interests: check whether the operating earnings include all of a consolidated subsidiary while common equity belongs only to the parent shareholders.
- Leases: align the financing treatment with the earnings measure and peer comparison.
- Investments and other non-operating assets: avoid including their value while excluding their earnings, or vice versa.
- Debt: consider the appropriate value for the purpose and disclose approximations rather than silently mixing book and market amounts.
Transaction purchase-price bridges can also contain debt-like items, working-capital adjustments and agreed definitions that differ from a simple trading enterprise-value calculation.
Match the valuation multiple to the claim
| Multiple | Why the pairing matters |
|---|---|
| Price / earnings | Common equity value is compared with earnings attributable to common shareholders |
| Enterprise value / EBITDA | The business value is compared with an operating earnings measure before interest |
| Enterprise value / revenue | The business value is compared with sales; margins and business differences still matter |
Do not divide enterprise value by net income merely because both figures are available. The numerator and denominator must refer to compatible claims, periods and business scope. A lower multiple by itself does not establish that a business is undervalued.
Can enterprise value be negative?
A conventional calculation can be negative when the cash deduction exceeds equity value and the other claims added. That result deserves investigation: check cash availability, expected cash use, omitted claims and the consistency of the inputs. It does not establish that an investor can acquire the business and receive free cash without risk.
Practice the bridge
A fictional business has enterprise value of 180, debt of 45, preferred equity of 5, non-controlling interests of 10 and cash of 20. What is common equity value?
Answer: 180 − 45 − 5 − 10 + 20 = 140. With 7 million common shares and amounts in millions, the simplified value per share is 20.
Before moving on, explain every addition and subtraction. Then test what happens if the cash amount changes, keeping the enterprise-value estimate and other assumptions fixed.
Further study
For definitions and consistency in valuation ratios, see Aswath Damodaran’s valuation definitions at NYU Stern. The financial modeling study plan places valuation after the operating forecast and statement links. You can also watch the video included with the original FinanceWalk explanation.


